

An employee asks you, “Does our health plan cover Wegovy or Zepbound?” Those are weight-loss medicines from a group called GLP-1s. Would you know the answer?
Doctors use GLP-1s for type 2 diabetes and for weight loss. Wegovy and Zepbound are the two approved for weight loss. They work, people want them and they’re expensive.
Picture two owners, each with about 40 people and a health plan that renews each year. One covers these medicines and thinks it’s the best thing the plan does. The other doesn’t, because covering them would take money out of everyone’s paycheck for something that’s hard to measure.
Both care about their people and made the call that fits their company.

The case for covering
The health benefit is real. A large trial followed about 17,600 adults who had heart disease and extra weight. Over about 40 months, it found about 20% fewer heart attacks, strokes and deaths from heart disease. In 2024, the Food and Drug Administration approved Wegovy for that use too.
The weight loss is large. In one trial, people lost about 17% of their weight on average over 68 weeks. People on a dummy treatment lost about 2%.
Your plan already covers other long-term conditions. It pays for medicines people take every day for years. Nobody asks them to explain themselves first. If your plan covers those and leaves this one out, it helps to be able to say why.
It can help you keep good people. Benefits are one of the few places a 40-person company can match a 4,000-person one. You can’t match their pay, but sometimes you can match their plan. People compare notes. More of them want access to these medicines every year.
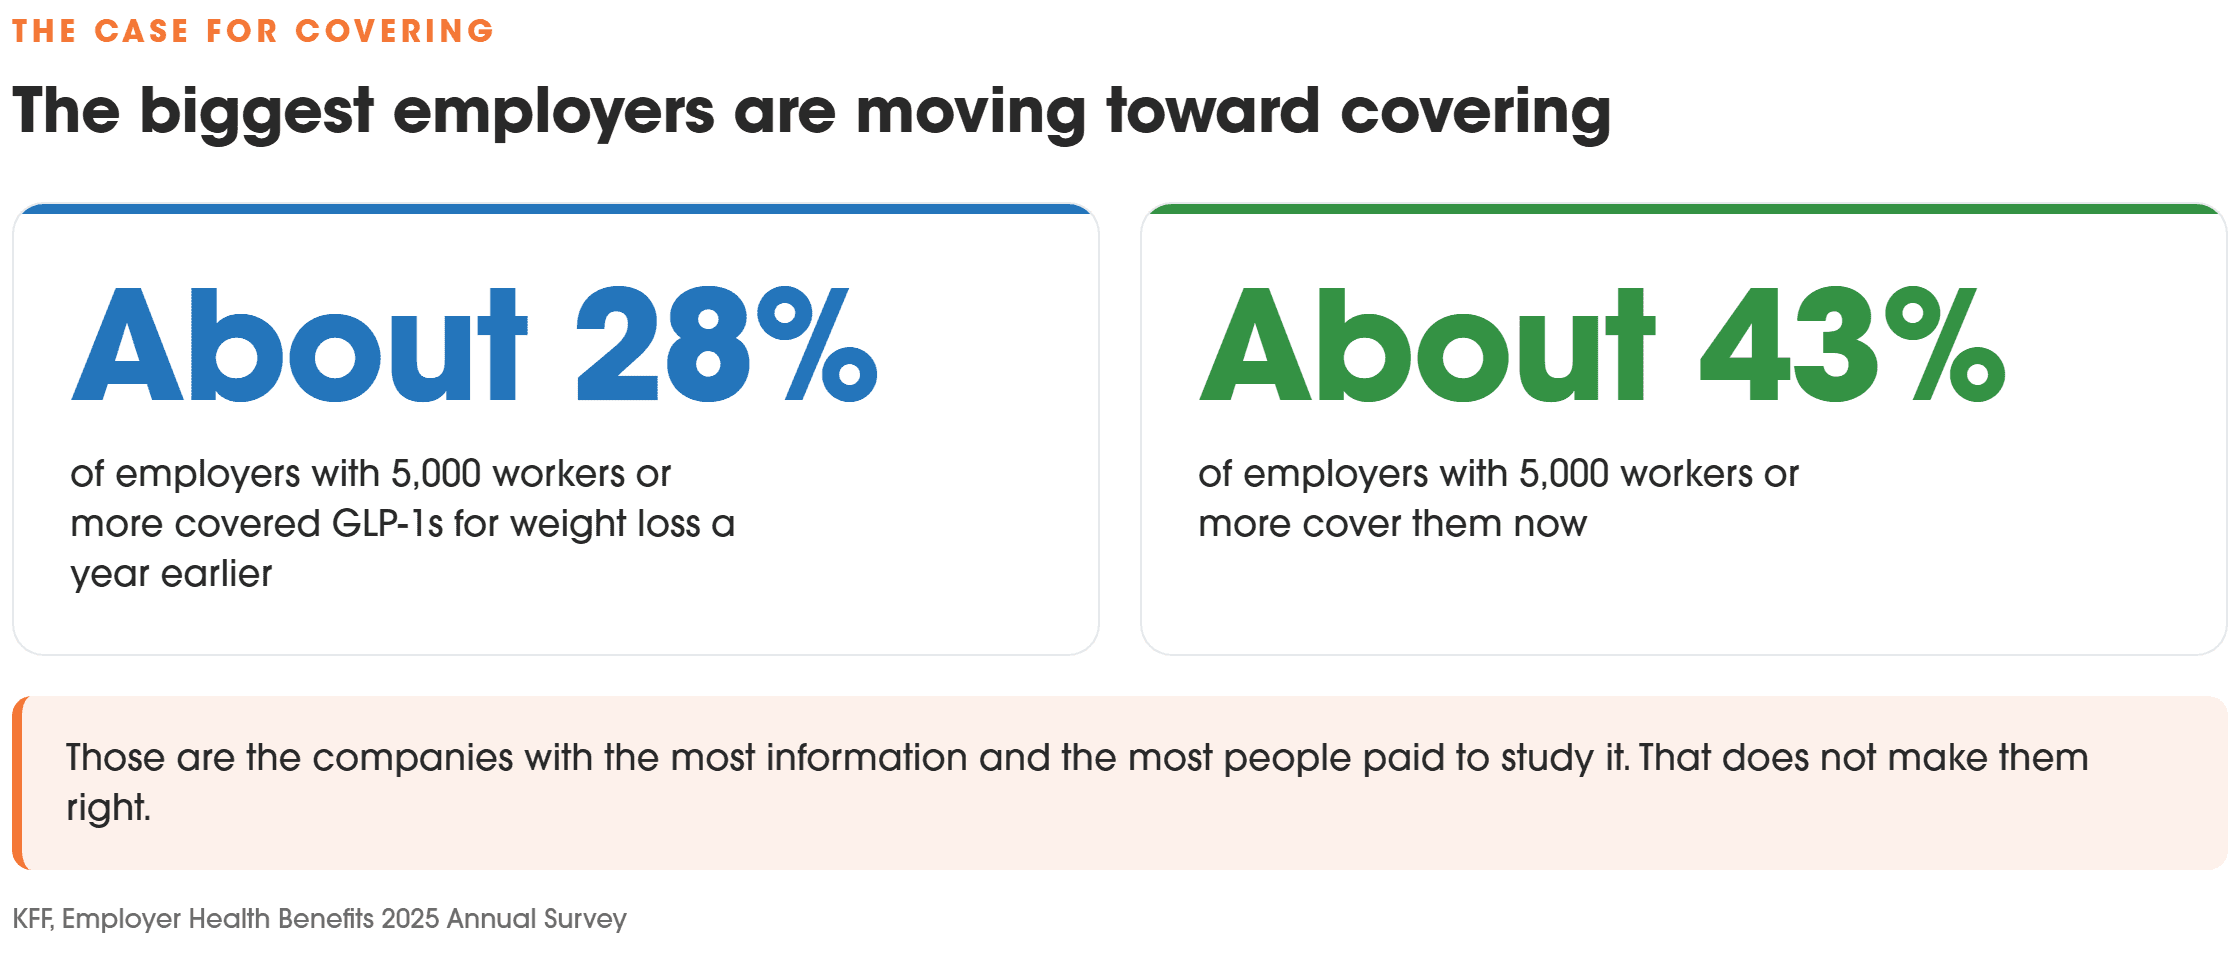
Big employers are moving toward covering. About 43% of employers with 5,000 or more workers now cover these medicines for weight loss, up from about 28% a year earlier. Big companies don’t always get it right, but this shows where things are heading.
Someone on your team may be waiting on this. For that person, coverage decides whether they can afford to follow their doctor’s advice.
Source: New England Journal of Medicine, “Semaglutide and Cardiovascular Outcomes in Obesity without Diabetes” (Lincoff AM et al., 2023)
Source: U.S. Food and Drug Administration, “FDA Approves First Treatment to Reduce Risk of Serious Heart Problems Specifically in Adults with Obesity or Overweight”
Source: Diabetes, Obesity and Metabolism, “Weight regain and cardiometabolic effects after withdrawal of semaglutide: The STEP 1 trial extension” (Wilding JPH et al., 2022)
Source: KFF, “Employer Health Benefits 2025 Annual Survey Summary of Findings”
The case against covering
Nobody has shown it pays for itself. No neutral source shows an employer saving money by covering these medicines. If someone shows you a payback number, ask who paid for the study.
It can raise what everyone pays. One study estimated that adding this coverage could raise the monthly price of an employer’s plan by between 5.3% and 13.8%. If the medicines cost less, the rise was between 1% and 3.9%. That study assumed no savings from fewer medical bills in the short run.
Your employees share that cost. At companies with 10 to 199 workers, employees pay about $8,889 a year on average toward family coverage. At bigger companies, it’s about $6,227. Your people already carry more of the cost than people at big companies. Adding to the plan’s price adds to what comes out of their paychecks, for a benefit some of them will never use.
The payoff may land somewhere else. People change jobs. A health benefit that shows up years from now may land on another company’s plan, while the cost lands on yours this year.
The money could do other jobs. The same money could lower the deductible, the amount people pay before the plan pays, for your whole team. It could also pay for support with weight and healthy habits. About 56% of employers with 10 to 199 workers offer a program to help people quit smoking, manage their weight or build healthy habits. About 83% of employers with 200 or more workers do. Many companies your size don’t offer that kind of support yet.
Many people stop taking them. In research reviewed by a New Jersey state commission, more than 68% of people didn’t stay on these medicines for a full year. A plan can pay for the costly first months again and again without the health benefit ever showing up. That’s nobody’s fault, but it’s real money.

Source: Employee Benefit Research Institute, “GLP-1 Coverage and Its Impact on Employment-Based Health Plan Premiums: A Simulation-Based Analysis”
Source: KFF, “Employer Health Benefits 2025 Annual Survey Summary of Findings”
Source: New Jersey Mandated Health Benefits Advisory Commission, “A Study of New Jersey Assembly Bill 5200”
What both sides have to live with
Either way, keep these three things in mind.
You’re deciding for more than one year. In one trial, a year after people stopped the medicine, they had regained about two-thirds of the weight they lost. So covering may mean paying for as long as people take it. If you don’t cover them, the same question comes back at every renewal.
Far more people could ask than ask today. In 2022, about 3% of working-age adults with health coverage through work filled a prescription for one of these medicines. More than 40% of adults with private health insurance could qualify. If more of your people start asking, your plan’s costs could change at your next few renewals.
Nobody tracks companies your size. The big national surveys only count employers with 200 or more workers. So the numbers you see in the news all come from companies bigger than yours.
Source: Diabetes, Obesity and Metabolism, “Weight regain and cardiometabolic effects after withdrawal of semaglutide: The STEP 1 trial extension” (Wilding JPH et al., 2022)
Source: Peterson-KFF Health System Tracker, “Perspectives from employers on the costs and issues associated with covering GLP-1 agonists for weight loss”
Source: KFF, “Employer Health Benefits 2025 Annual Survey Summary of Findings”
So what should you do?
The answer depends on your plan, your people and your numbers.
Your plan. What it covers today may not be what you think. The answer is often tucked in the list of what the plan doesn’t cover, not the list of drugs it does.
Your people. You know your 40 people better than any survey does. If you want to know what matters to them, ask them.
Your numbers. It comes down to how many of your people would use it and how the cost is split. It also depends on the rules you set, like having the plan check with the doctor before it pays.
Here’s a simple way to work through it:
1) Find out what your plan does today for weight loss, not just for GLP-1s in general.
2) Find out what your plan spends on these medicines. On a standard plan, the insurance company usually won’t share that number. Pennworth can tell you what you can see on your plan.
3) Look at the middle options. For example, a plan can cover these medicines only after it checks with the doctor, only for people with diabetes, or only alongside a weight program.
At Pennworth, we won’t tell you whether to cover these medicines. That’s your call, because you’re the one who stands behind it with your team. We’ll show you what your plan does, what it costs, what your choices are and what each one gives up. Then you can decide what’s right for your team and your budget.
Want a quick read on your whole benefits plan first? Start with the 2-minute assessment below.
See where you stand
Answer 7 quick questions and see how healthy your benefits program is. It takes 2 minutes.
Let’s Talk
See what it’s like to have the benefits department you don’t have to build.
A 20-minute Zoom. No pressure, no obligation.


